The Clarity for Compensation Act amends the Securities Exchange Act of 1934 to allow registered representatives to receive compensation through personal services entities without those entities being classified as brokers.
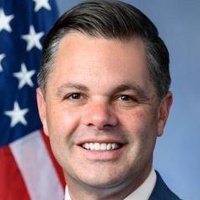
Zachary (Zach) Nunn
Representative
IA-3
The Clarity for Compensation Act amends the Securities Exchange Act of 1934 to allow registered representatives to receive compensation through personal services entities without those entities being classified as brokers. This legislation establishes clear regulatory guardrails, including strict oversight, supervision, and liability requirements, to ensure these entities remain accountable for securities-related activities.
Clarity for Compensation Act: New Rules for How Financial Advisors Get Paid Take Effect in 180 Days
The Clarity for Compensation Act creates a specific legal carve-out for personal services entities—companies set up by financial advisors to manage their business income. Under current law, the definition of a 'broker' is broad, but this bill amends Section 3(a)(4) of the Securities Exchange Act of 1934 to ensure these small, advisor-owned companies aren't buried in the same heavy-duty regulations as major Wall Street firms. By allowing a registered representative to direct their commissions to their own LLC or S-Corp without that entity being labeled a 'broker,' the bill simplifies how advisors handle their taxes and business expenses.
The Advisor’s Side Hustle Structure
Think of your local financial advisor, the person who helps you pick mutual funds or manage your IRA. Many of these professionals set up their own small businesses to handle their paychecks and office costs. This bill says these entities are safe from being treated as full-blown brokerage firms as long as they follow strict rules: the entity must be owned exclusively by the advisor or their immediate family, it can’t pretend to be a broker to the public, and it can’t do anything other than receive pay for the advisor’s work. For an advisor, this means less red tape when trying to manage their personal business finances, but it requires a formal written agreement with their parent brokerage firm to keep everything above board.
Protecting the Client’s Pocketbook
If you’re a client, you might wonder if this makes it harder to sue if something goes wrong. The bill tries to close that loophole by requiring these personal entities to submit to the jurisdiction of the same dispute resolution forums (like FINRA) that govern the advisors themselves. Specifically, the entity must agree in writing to be bound by any awards issued against the advisor, using whatever assets the entity holds to satisfy those claims. While this is meant to protect you, the bill uses the phrase 'adequate supervision and control' to describe the parent broker’s responsibility. This is a bit vague—it doesn't list specific checklists for what 'adequate' looks like, which means the quality of oversight could vary depending on the firm.
Records, Rules, and Realities
To keep things transparent, these personal companies must keep the same books and records that the SEC or self-regulatory organizations require from the main brokerage firms. If a regulator comes knocking, the advisor has to show exactly where the money went. The bill also gives the SEC the power to add 'additional requirements' down the road, which keeps the door open for more rules if people start using these entities to hide shady activity. For the busy professional just trying to save for retirement, these changes happen mostly behind the scenes, but they ensure that the person managing your money has a clear, legal way to run their business without losing the accountability that protects your investments.