This bill clarifies that federal income tax exemptions for nonprofits and certain retirement plans do not constitute "federal financial assistance" under federal law.
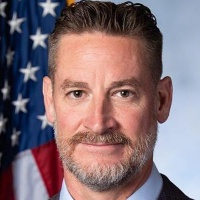
W. Steube
Representative
FL-17
The Safeguarding America’s Nonprofits Act clarifies that federal tax-exempt status for nonprofits and similar organizations does not constitute "federal financial assistance." This ensures that these organizations are not subject to federal regulations or requirements triggered specifically by the receipt of government financial aid.
Nonprofit Tax Status Shielded: New Bill Decouples Tax Exemptions from Federal Financial Assistance Rules
The Safeguarding America’s Nonprofits Act aims to draw a hard line between a tax break and a government check. Under Section 2, the bill amends the Internal Revenue Code to clarify that being exempt from federal income tax—specifically for 501(c), 501(d), and 401(a) organizations—does not count as receiving "Federal financial assistance." This might sound like a technicality, but it’s a significant legal firewall. By stating that tax-exempt status isn't the same as a government grant or loan, the bill ensures that these organizations aren't automatically subject to the same strings and regulatory hoops that come with direct federal funding, unless a specific law says otherwise.
Drawing the Line on Regulation
Think of it this way: if you’re a local food bank or a church-run daycare, you likely have a 501(c)(3) status so you don't pay federal income tax. Currently, there is a legal grey area where some might argue that this tax break is a form of government subsidy, which could potentially trigger a massive list of federal compliance rules usually reserved for entities that take actual cash from the Treasury. This bill shuts that door. It clarifies that simply keeping more of your own money through an exemption isn't the same as the government handing you a taxpayer-funded grant. For the administrator of a local nonprofit or a manager of a 401(k) retirement trust, this means one less layer of potential bureaucratic red tape to worry about when navigating federal regulations.
Clear Rules for the Road Ahead
The bill is also very specific about how this applies to the past and future. It includes a "Rule of Construction" stating that this new definition doesn't imply that tax exemptions were considered federal assistance before this act was passed. It’s essentially a "no looking back" clause designed to prevent lawyers from digging through old records to find violations based on the previous ambiguity. Whether you are a software engineer contributing to a 401(a) retirement plan or a trade worker volunteering for a 501(c) community group, the bill provides a steady legal environment where these organizations can operate without the sudden risk of being reclassified as federal contractors or grant recipients just because they don't pay income tax.